 ProMapRanker
Philippines Best Loan Apps in 2026

Active GCash users who want cash in their wallet · Pricing starts at: From 1.59% per month
Key takeaways
- The cheapest advertised rate on this list is Maya Personal Loan at as low as 0.77% monthly add-on (1.40% monthly effective rate) on a 24-month term, but it asks salaried borrowers for a pay slip or similar proof of income.
- GCash GLoan advertises rates as low as 1.59% per month, with a 3% processing fee deducted when you take the loan.
- Small, short loans cost far more. Cashalo says that from April 1, 2026, its loans of ₱10,000 or less with terms of 4 months or shorter carry an effective rate of 12% per month.
- MoneyCat lists 11.9% interest per month and a maximum APR of 145%, which makes it a last resort rather than a first choice.
- Every app here shows its SEC registration or BSP license on its own website. Check that number before you share any personal data.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
| GCash GLoan | Active GCash users who want cash in their wallet | From 1.59% per month | No | Visit |
 Maya Personal Loan | Bigger loans at the lowest advertised rate | From 0.77% monthly add-on rate | No | Visit |
 Tonik Credit Builder Loan | Building a credit history with a bank | From 4.20% monthly add-on rate | No | Visit |
 BillEase | Installments for shopping and cash | 0% to 5% per month | No | Visit |
 Tala | First-time borrowers with one ID | See website | No | Visit |
 Cashalo | Small emergency loans | 12% per month effective (small loans) | No | Visit |
 JuanHand | Fast loans up to ₱50,000 | See website | No | Visit |
 Digido | A short first loan at 0% interest | 0% for the first 7-day loan | No | Visit |
 MoneyCat | Borrowers who have run out of cheaper options | 11.9% per month | No | Visit |
The best loan apps in the Philippines
These are the Philippines best loan apps we found that are licensed, still operating in October 2026, and open about their limits and rates on their own websites. This is general information, not financial advice. Borrowing costs money, and missing payments adds penalties, so only borrow what you can repay on time.
If you already pay bills and send money with GCash, GLoan is the most convenient place to start. GCash says the loan is powered by Fuse Financing, Inc., which is regulated by the SEC, and you apply inside the GCash app with no extra documents.
The page advertises loans up to ₱150,000, and its calculator runs up to ₱125,000. The standard interest rate shown is 1.59% per month, though GCash says the rate may vary per user. A 3% processing fee is deducted when the loan is released, so a ₱10,000 loan puts about ₱9,700 in your wallet.
The catch is eligibility. GCash says the amount you can borrow depends on your GScore and your GCash transactions, so a new or light user may not see a GLoan offer at all.
- Interest as low as 1.59% per month
- No extra documents or collateral
- Money goes straight to your GCash wallet
- 3% processing fee is deducted upfront
- You only qualify if your GScore is high enough
Maya Personal Loan is the pick for people who need a larger amount and have steady paperwork. Maya Bank's borrow page lists loan offers from ₱15,000 to ₱250,000, payable in 6 to 24 monthly installments.
The advertised rate is as low as 0.77% monthly add-on for 24 months, which Maya says equals a 1.40% monthly effective interest rate. That is the lowest advertised rate we found among these apps. Maya also offers Easy Credit, a credit line of up to ₱50,000 with no documents and up to 30 days to pay, charged through a service fee instead of interest.
The honest catch is paperwork. Salaried borrowers need a recent pay slip, certificate of employment or ITR, and self-employed borrowers need proof of income and business registration. Shorter terms will also carry a higher monthly rate than the headline figure.
- Loans from ₱15,000 to ₱250,000
- As low as 0.77% monthly add-on rate on 24 months
- Issued by a bank
- Needs proof of income such as a pay slip or ITR
- Lowest rate applies only to the longest term
Tonik is a digital bank, and its Credit Builder Loan is aimed at Filipinos who have little or no credit history. Tonik's page says the loan needs no credit history or collateral, just one valid ID and a Tonik account, and that using the account regularly helps you qualify.
You can borrow up to ₱50,000 over 6, 9 or 12 months. Tonik lists the rate as low as 4.20% monthly add-on, and there are no pre-termination fees if you pay early. Applicants must be 23 to 58 years old with a valid TIN.
Where Tonik falls short is cost. A 4.20% monthly add-on rate adds up fast over a year, so compare the total amount payable in the app before you accept.
- BSP-licensed and PDIC-insured bank
- Up to ₱50,000 with 6, 9 or 12 month terms
- No pre-termination fees
- Monthly add-on rate is much higher than Maya's
- You need a Tonik account and a TIN
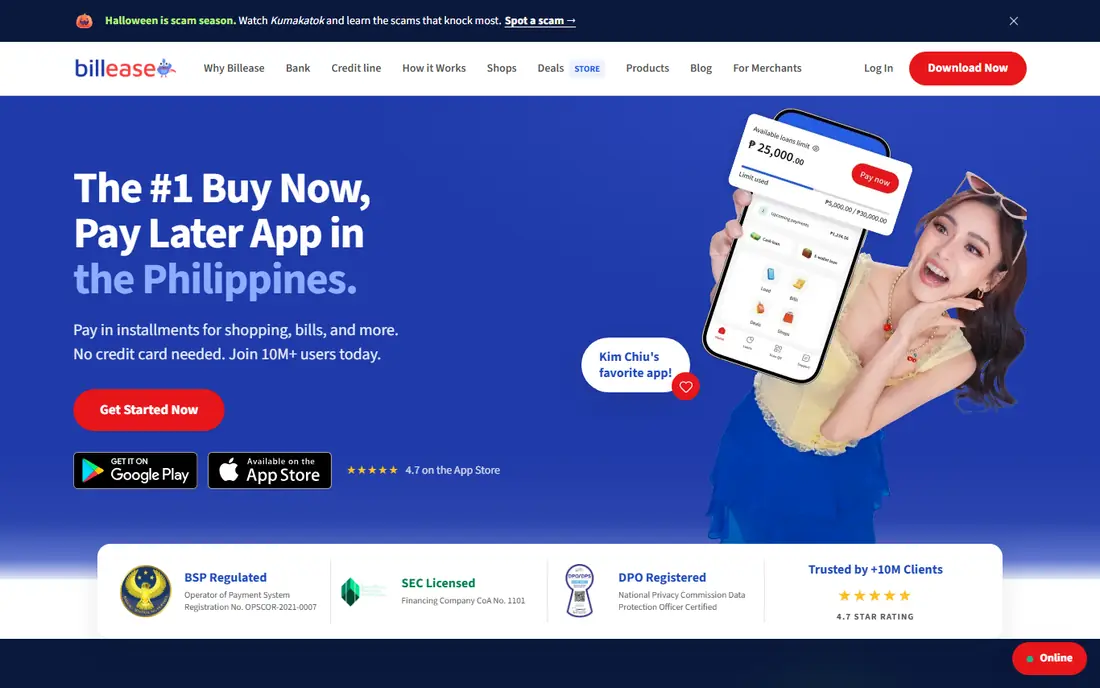
BillEase started as a buy now, pay later app and still works best for that. You can split online and in-store purchases into installments, with 0% interest at select partner merchants, and its cash loan sends money to your bank or e-wallet.
Its site lists monthly interest from 0% to 5% and a credit limit up to ₱50,000. BillEase is run by First Digital Finance Corporation, an SEC-licensed financing company (CoA No. 1101), and is a BSP-registered operator of a payment system.
The downside is that your real terms only appear inside the app. First-time borrowers are limited to shorter terms, since the 12 and 24 month options are labeled for repeat customers only.
- Cash loans from ₱2,000 to ₱50,000
- 0% at select partner merchants
- SEC-licensed and BSP-registered payment operator
- Longer 12 and 24 month terms are for repeat customers only
- Exact rate only shows in the app
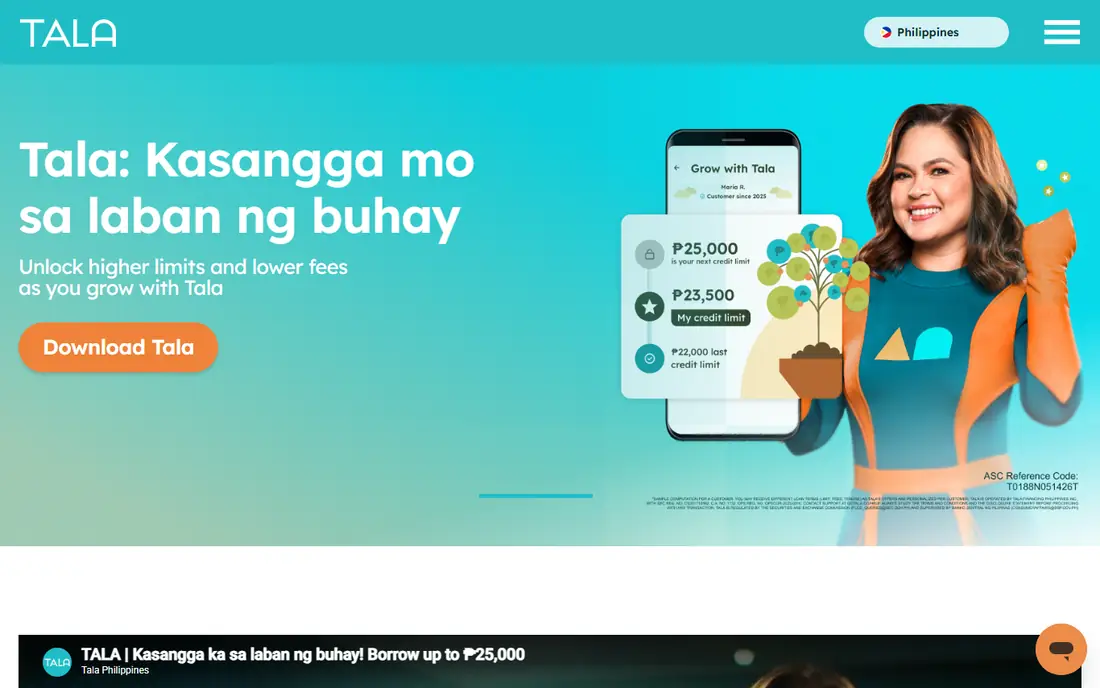
Tala is built for people who cannot get a bank loan yet. Its site says you can apply in minutes, get an instant decision and cash out through disbursement channels nationwide, with limits that grow up to ₱25,000 as you repay on time.
Tala is operated by Tala Financing Philippines Inc., a licensed financing company (SEC Registration No. CS201710582, Certificate of Authority No. 1132). You can pick your own repayment date up to 61 days, which helps if your income is irregular.
The honest weakness is cost transparency. Tala says there are no hidden fees, but the homepage does not show a rate, so read the disclosure statement in the app before accepting. Expect your first offer to be small.
- One valid ID to apply
- Choose a repayment date up to 61 days
- Limits grow up to ₱25,000 with on-time repayment
- Fees are not listed on the homepage
- First loans can be very small
Cashalo is a small-loan app run by Paloo Financing, Inc. (SEC Registration No. CS201800209, Certificate of Authority No. 1162). Its loans start at ₱1,000 and go up to ₱13,000 for customers with a good repayment record.
We give Cashalo credit for spelling out the price. Its site says that from April 1, 2026, in line with SEC Memorandum Circular No. 14 (2025), loans of ₱10,000 or less with terms of 4 months or shorter have an effective rate of 12% per month. That includes a 0.2% daily interest and a 0.2% daily service fee, and late payments add charges on top.
That honesty also shows the problem. Twelve percent a month is expensive, so Cashalo only makes sense for a real emergency you can repay quickly.
- Clear rate disclosure on its site
- SEC-registered financing company
- Loans start at ₱1,000
- Loan cap is only ₱13,000
- Small short loans cost 12% per month
JuanHand is one of the bigger lending apps in the country, and it says it has more than 20 million active users. It is SEC-registered (Registration No. CS201825672, CA No. 2844) and says it complies with the National Privacy Commission and AMLC rules.
The app needs a registered mobile number and one valid ID, and JuanHand says approval can take as little as 5 minutes. New borrowers may get their first installment interest-free under a current promotion. We also like that the site warns plainly that JuanHand never asks for processing fees to release a loan.
Our concern is the headline rate. The homepage says the interest rate is as low as 0.025% without saying whether that is per day or per month, so check the disclosure statement in the app for the real effective rate.
- Borrow up to ₱50,000 with one valid ID
- First-installment interest-free promo for new users
- Clear anti-scam warnings
- Advertised "as low as 0.025%" rate does not say per what period
- Real rate depends on your offer
Digido's best feature is its first-loan offer: 0% interest for 7 days. That makes it useful for a one-time gap before payday, as long as you repay on time.
Repeat borrowers can get up to ₱25,000 for up to 180 days. Applicants must be Filipino residents aged 21 to 70 who are employed or in selected professions, and the site says no guarantors or deposits are needed. Digido Finance Corp. is SEC-registered (Registration No. CS202003056, Certificate of Authority No. 1272).
The catch is that the free loan is short and small. After that, standard rates apply, so read the terms for your second loan carefully. Support is listed as Monday to Friday, 8am to 5pm.
- First loan at 0% interest for 7 days
- Repeat loans up to ₱25,000 for up to 180 days
- No guarantors or deposits
- The 0% offer only covers a short first loan
- Support hours are weekdays only
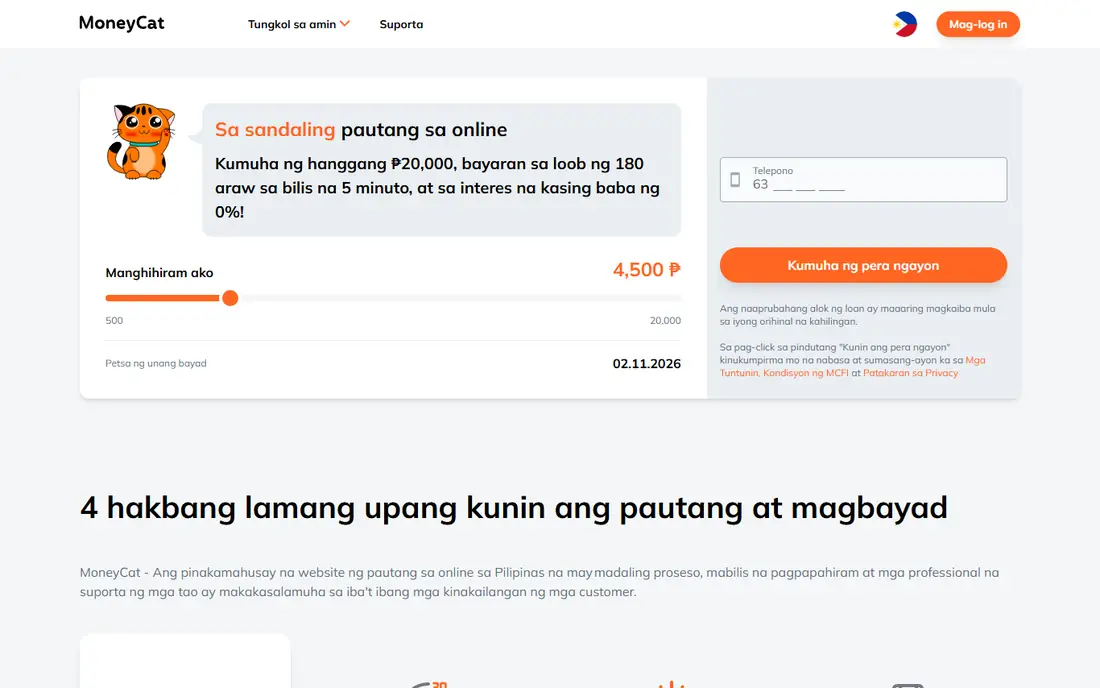
MoneyCat is on this list because it is licensed and upfront about cost, not because it is cheap. MoneyCat Financing Inc. lists SEC Registration No. CS201953073 and Certificate of Authority No. 1254 on its site.
You can borrow ₱500 to ₱20,000 over 3 to 6 months. The homepage lists an interest rate of 11.9% per month with a maximum APR of 145%, and it says the approved amount may differ from what you asked for. Applicants must be at least 22 years old.
That rate is the honest warning. Use MoneyCat only if the apps above have turned you down and the need is real, and borrow the smallest amount you can.
- Loans from ₱500 to ₱20,000
- 3 to 6 month terms
- Rate and maximum APR shown on the homepage
- 11.9% per month and up to 145% APR is expensive
- Site is mostly in Filipino
How we picked these
We looked for lending apps that show an SEC registration number and Certificate of Authority, or a BSP license, on their own websites. We then read each lender's official site in October 2026 for loan limits, terms, advertised rates, fees and eligibility rules. We also used the BSP's published caps for small loans and Cashalo's disclosure of the 2026 SEC rule as a yardstick for what counts as expensive.
We did not take out loans with these apps. Where a lender did not publish a rate we could verify, we wrote See website. We left out lenders whose sites we could not load or verify during our check.
How to borrow safely from a loan app
Check the license first
Every legitimate online lender in the Philippines should show its SEC registration number and Certificate of Authority, or a BSP license if it is a bank. Look the company up on the SEC website before you install the app or share your ID.
Compare the effective rate, not the add-on rate
An add-on rate is charged on the original amount for the whole term, so the true cost is higher than it looks. Maya, for example, says its 0.77% monthly add-on rate equals a 1.40% monthly effective rate. Always compare effective rates and the total amount you will repay.
Know the small-loan caps
BSP Circular No. 1133 caps small loans from BSP-supervised lenders of ₱10,000 or less with terms of up to 4 months at 6% nominal interest per month, 15% effective interest per month, and total costs of 100% of the amount borrowed. Cashalo says the SEC's Memorandum Circular No. 14 (2025) also changed small-loan pricing for financing companies from April 2026.
Watch for scams
Real lenders do not ask you to pay a processing fee before releasing a loan. JuanHand and BillEase both warn about scammers posing as their staff and asking for codes or fees. Never share a one-time PIN with anyone.
Frequently asked questions
What are the best loan apps in the Philippines right now?
For low rates, Maya Personal Loan and GCash GLoan lead this list, as long as you qualify. For first-time borrowers with limited paperwork, Tala, BillEase and Tonik are easier to get into. Check each app's license number before applying.
Which loan app in the Philippines has the lowest interest?
Among the apps we checked, Maya Personal Loan advertises the lowest rate at as low as 0.77% monthly add-on for 24 months, or 1.40% effective per month. Digido offers 0% on a first 7-day loan, but that is a one-time promotion. Your actual rate depends on your credit profile.
Can I get a loan app approval with just one valid ID?
Yes, several apps say one valid ID is enough to apply, including Tala, JuanHand and Tonik (which also needs a Tonik account and TIN). Approval is still not guaranteed, and first loans are usually small.
How do I know if a loan app is legit?
Look for the SEC registration number and Certificate of Authority on the lender's website or app, then confirm it on the SEC website. Be wary of any app that asks for upfront fees, requests your contacts, or pressures you with threats.
What happens if I miss a payment?
Lenders add penalty charges, and repeated late payments can lower your limit or credit score. BSP Circular No. 1133 caps late-payment penalties on small loans from BSP-supervised lenders at 5% per month on the overdue amount. Contact your lender early if you know you will be late.
Sources
- https://www.gcash.com/services/gloan
- https://www.mayabank.ph/borrow/
- https://tonikbank.com/loans
- https://billease.ph/
- https://tala.ph
- https://www.cashalo.com
- https://www.cashalo.com/cash-loan
- https://www.juanhand.com
- https://digido.ph
- https://moneycat.ph
- https://www.bsp.gov.ph/Regulations/Issuances/2021/1133.pdf
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 best secret management tools enterprise devsecops
Best Secret Management Tools for Enterprise DevSecOps in 2026
The best secret management tools for enterprise DevSecOps in 2026, compared on pricing, free tiers, rotation, dynamic secrets and self-hosting, from Vault to Infisical.
Read → best png to svg free tool
Best PNG to SVG Free Tool in 2026
Looking for the best PNG to SVG free tool? We compared 7 free converters in 2026, from Inkscape and SVGcode to Adobe Express, on tracing quality, limits and privacy.
Read → best gold ira companies
Best Gold IRA Companies in 2026
Comparing the best gold IRA companies for 2026 on published minimums, annual fees, buyback terms and pricing transparency, from Noble Gold to American Hartford Gold.
Read →